Weekly Trading Analysis – Week Ending 2026-10-18 #
1. Weekly Summary #
| Metric | Current Week | Last Week | Change ($) | Change (%) |
|---|---|---|---|---|
| Total Portfolio Value | $285,485.12 | $289,697.84 | -$4,212.72 | -1.45% |
| IBKR Portfolio Market Value | $81,780 | $84,230 | -$2,450 | -2.91% |
| Binance Portfolio Value (USDC) | $203,705.12 | $205,467.84 | -$1,762.72 | -0.86% |
| IBKR Buying Power | $449,300 | $460,900 | -$11,600 | -2.52% |
| IBKR Unrealized P&L | -$17,600 | -$16,800 | -$800 | — |
| IBKR Total Cash | $46,900 | $59,100 | -$12,200 | -20.64% |
| Binance EUR Value | €181,486.72 | €183,569.61 | -€2,082.89 | -1.13% |
Overall P&L: total portfolio declined $4,212.72 (-1.45%). IBKR unrealized P&L worsened by $800 to -$17,600. Binance floating P&L is only partially reported (EURI +$10.49, G —, others NA).
2. Open Positions #
IBKR Positions #
| Symbol | Quantity | Cost Basis | Market Value | Unrealized P&L | WoW Change |
|---|---|---|---|---|---|
| ATOS | 80 (0) | $3,542 (0) | $238.40 (+$46.40) | -$3,304 (+$46.00) | Improved |
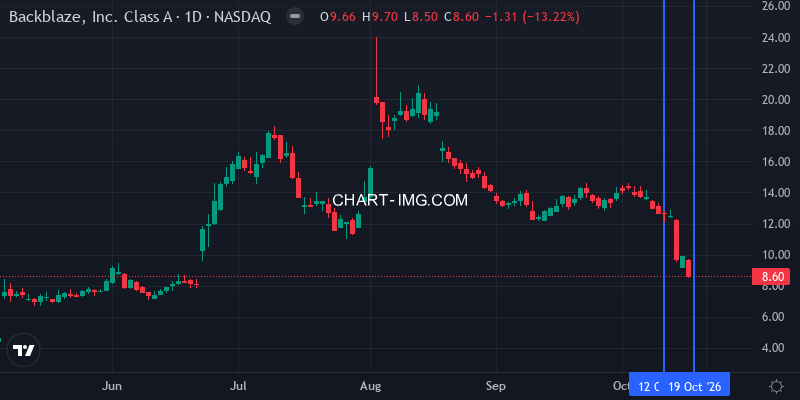
| BLZE | 600 (+500) | $8,000 (+$5,729) | $5,220 (+$3,944) | -$2,780 (-$1,784.84) | Worse |
| PSFE | 50 (0) | $2,992 (0) | $283.00 (-$5.50) | -$2,709 (-$5.00) | Slightly worse |
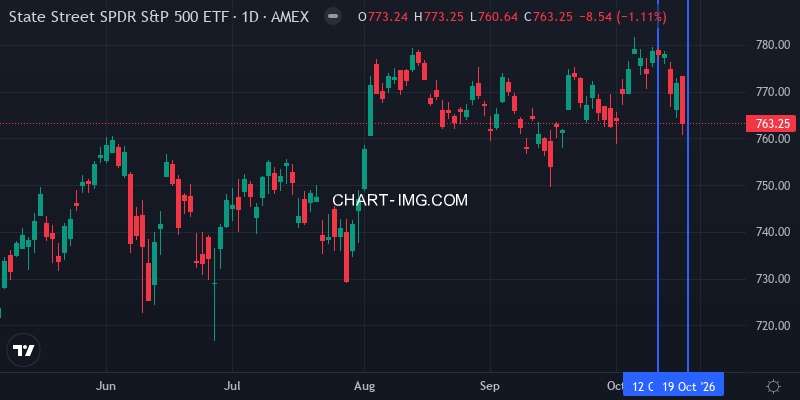
| SPY Nov 727/737 810/820 Iron Condor | 1 (new) | -$188.83 (new) | -$161.63 (new) | +$27.19 (new) | New |
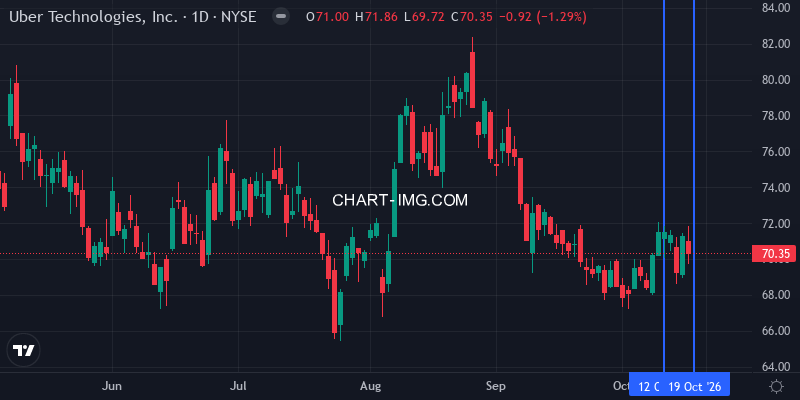
| UBER | 500 (0) | $46,048 (0) | $34,985 (-$699) | -$11,063 (-$699) | Worse |
| UBER Nov 20 ‘26 72.5 Call | -5 (0) | -$1,467 (0) | -$1,423 (+$305) | +$43.70 (+$305.40) | Improved |
Binance Positions #
| Symbol | Quantity | Cost Basis | Market Value (USDC) | Floating P&L | WoW Change |
|---|---|---|---|---|---|
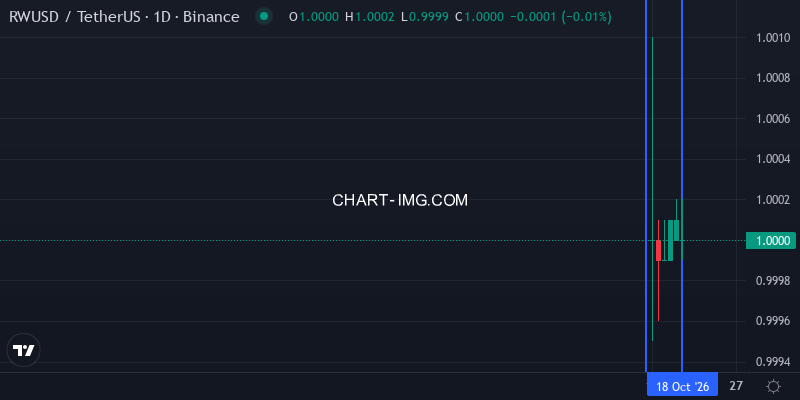
| RWUSD | 131,750.9673 (+91.17) | N/A | $131,584.07 (-$78.44) | NA | Slightly lower |
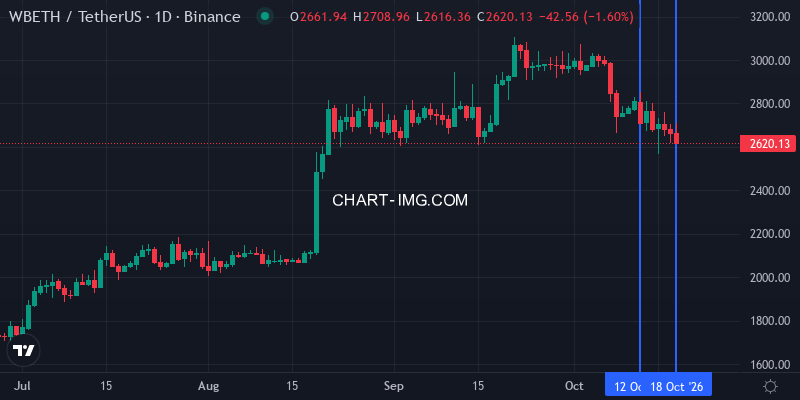
| WBETH | 26.32907119 (0) | N/A | $71,060.50 (-$1,619.47) | NA | Lower |
| GRAM | 510.84542428 (+0.098) | N/A | $688.77 (-$55.30) | NA | Lower |
| EURI | 261.93061759 (+0.055) | N/A | $294.17 (+$1.21) | +$10.49 (+$0.58) | Slightly higher |
| G | 16,089.787107 (0) | N/A | $61.39 (-$8.22) | — | Lower |
| CATI | 190.34564294 (0) | N/A | $10.15 (-$1.91) | NA | Lower |
Cost basis not provided in Binance export.
3. Positions Entered This Week #
| Symbol | Details |
|---|---|
| SPY Nov 727/737 810/820 Iron Condor | Opened 1 lot for $193 credit; currently +$27.19 net. |
| BLZE (additional shares) | +500 shares via assignment of short puts; position increased from 100 to 600. |
4. Positions Closed This Week #
| Symbol | Details |
|---|---|
| SPCX Oct 125/140 Bull Call (bear call) | Closed at 15.00; realized -$1,447 on this leg (approx -$7,160 across whole SPCX trade including Sep roll). |
| BLZE Oct 16 ‘26 12.5 Put | 5 short puts assigned/expired; 3 early on Oct 15, 2 at expiry; added 500 BLZE at $12.50. |
5. Analysis / Notes #
- Total portfolio fell $4,212.72 (-1.45%) to $285,485.12. IBKR lost $2,450 and Binance lost $1,762.72 in USDC terms.
- IBKR cash dropped $12,200 to $46,900, reflecting the BLZE assignment and SPCX close. Buying power fell $11,600.
- UBER remains the largest drag: long 500 shares are -$11,063 unrealized, down $699 this week. The short Nov 20 ‘26 72.5 call improved by $305.40 to +$43.70 as UBER declined, but the stock loss dominates.
- BLZE saw a major change: assignment of 5 short puts added 500 shares at $12.50, bringing the position to 600 shares with a blended cost basis of $13.33. Current market value implies a price of $8.70, so the position is -$2,780, worsening by $1,784.84 this week. The put premium received earlier reduced the effective cost basis but the stock is still well below breakeven.
- SPY Iron Condor (Nov 20 727/737 put spread, 810/820 call spread) was opened for a $193 credit. With SPY at 761, the 737 put side is the closest to the money and the key risk to monitor. Current net P&L is +$27.19.
- SPCX was closed for a realized -$1,447 on this leg, removing a losing options position. The total SPCX trade including the September roll is approximately -$7,160.
- Binance: WBETH fell $1,619.47, the largest crypto decline. RWUSD was nearly flat (-$78.44). EURI posted a small gain (+$1.21, +$0.58 P&L). G and CATI drifted lower.
- Options performance: The UBER short call is now profitable, the SPY condor is slightly green, but the closed SPCX and assigned BLZE puts were the main options-related losses this week.
📊 Charts #
📝 Notes #
SPCX trade — post-mortem (closed 2026-10-16) #
Instrument: SPCX = Space Exploration Technologies Corp, Class A (NASDAQ; SpaceX IPO’d 2026-06-12 at $135).
Structure: a bear call spread, short 5 × SPCX 125 call / long 5 × SPCX 140 call (15-wide, 5 contracts). Opened around early August 2026 for a $1,674 net credit. (The weekly posts label this a “Bull Call” — that is wrong: short the lower strike = bear call.) It was rolled Sep→Oct on 2026-09-20, and finally closed on 2026-10-16 at a 15.00 debit (the full width = max loss).
Realized P&L:
- Sep leg, closed in the 2026-09-20 roll: −$5,712.74 (Sep 125C −$7,741.85, Sep 140C +$2,029.11).
- Oct leg, closed 2026-10-16 at 15.00: −$1,447 (opened for a $6,053 credit; paid $7,500 to close).
- Total realized on SPCX ≈ −$7,160 (plus commissions).
Price path vs. the spread (weekly SPCX close → mark of the 125/140 spread):
| Week (Fri) | SPCX close | SPCX spread P/L | Note |
|---|---|---|---|
| 2026-08-07 | 133.11 | — | spread opened (~Aug 5–9), $1,674 credit |
| 2026-08-14 | 140.00 | −$1,661 | SPCX reclaims 140 |
| 2026-08-21 | 136.97 | −$2,691 | |
| 2026-08-28 | 141.50 | −$2,525 | |
| 2026-09-04 | 147.95 | −$3,655 | |
| 2026-09-11 | 151.21 | −$4,833 | |
| 2026-09-18 | 152.71 | −$5,486 | Sep leg rolled to Oct |
| 2026-09-25 | 148.68 | −$293 | new Oct 125/140 spread |
| 2026-10-02 | 158.96 | −$1,274 | |
| 2026-10-09 | 162.57 | −$1,416 | |
| 2026-10-16 | 145.92 | −$1,447 (realized) | closed at 15.00 |
What happened. The trade was a defined-risk bet that SPCX would not run through 140. SpaceX instead rallied hard after its June IPO — insider-share unlocks and Tesla–SpaceX merger speculation — from ~$133 in early August to ~$150–162 by September/October (peaking near $171 mid-October before pulling back to ~$146). With SPCX persistently above 140, the short 125/140 spread sat at (or near) its maximum loss for most of its life; a defined-risk spread can’t lose more, but it also can’t recover once the underlying is pinned above the long strike.
Management review.
- The one decisive mistake was not cutting the tested spread early. The 2026-08-16 post already flagged it as “the biggest concern… may need management before September expiration.” It was instead rolled (Sep→Oct) on 2026-09-20, realizing −$5,713 and re-opening the same losing structure at the same strikes — a classic “roll the loser” that just paid to extend the pain.
- The final close on 2026-10-16 was correct: with SPCX ~$146 and expiry that day, −$1,450 (max loss) was the outcome whether held or closed; closing simply removed assignment/expiry mechanics on a deeply ITM short call.
- Execution detail: the closing order rested at 14.30, then 14.60, then filled at 15.00 as the combo drifted up — a reminder that on expiry day there is no theta left to earn and a passive limit on a deep-ITM spread is a bet that the underlying keeps falling.
Takeaways.
- A short-dated credit spread that is already ITM with the underlying trending against it is a thesis that has failed — cut it or re-strike, don’t roll it forward at the same strikes.
- Rolling a max-loss spread forward converts a defined loss into a defined loss plus a fresh position with the same directional bias.
- On expiry day, price to get out (near mid/marketable) rather than to save the last few cents.
- Very-high-IV names (SPCX options ran ~100–140% IV) tempt large credits, but the same IV means the underlying can move through the strikes quickly.
SPY Nov20 iron condor (opened 2026-10-12) #
Structure: short SPY Nov 20 ‘26 737 put / 810 call, long 727 put / 820 call — 1 contract, $10-wide wings. Opened 2026-10-12 at a $1.93 credit ($193; $188.83 net of $4.17 commissions). This is the 0.15Δ rung of the condor plan: breakevens 735.07 / 811.93, max loss $811.
Status (2026-10-18): SPY 761.26, down ~2% from the 777 entry. Mark ≈ 1.61 → P/L ≈ +$27 net (mid +$32). The put side is doing the work — short 737P 3.54 → 6.91, long 727P 2.79 → 5.56 (put spread 0.75 → 1.35) — while the call side decayed hard (810C 2.17 → 0.51, 820C 0.99 → 0.24). The short put sits ~3.2% below spot.
Plan: take +50% (~$96), hard-stop at −2× credit (−$386), roll/close at 21 DTE (2026-10-30). 0.15Δ was chosen deliberately: it is the only rung with positive expectancy at a 2×-credit stop (SPY 0.15Δ ≈ +$62/contract); 0.20Δ turns negative.
BLZE Oct 12.5 puts — assignment (2026-10-15 / 10-17) #
Position: short 5 × BLZE Oct 16 ‘26 12.5 puts (sold for ~$1.04 avg → ~$520 total credit), on top of 100 pre-existing BLZE shares.
What happened: BLZE traded below 12.50 into expiry, so all five puts were assigned:
- 2026-10-15: 3 contracts assigned early → bought 300 BLZE @ 12.50 ($3,750).
- 2026-10-17 (expiry settle): remaining 2 assigned → bought 200 BLZE @ 12.50 ($2,500).
Result: +500 shares at 12.50, taking the position to 600 BLZE @ $13.33 blended (cost basis $7,999.60). With BLZE at 8.65 (2026-10-18), unrealized −$2,810 (−35%).
Notes: this is what a cash-secured put is for — you accept the shares at the strike — but BLZE’s very high IV (≈100%+) and the slide from 12.5 → 8.65 meant the ~$520 premium barely dented the drawdown. The early assignment on 3 of the 5 contracts also surrendered the remaining extrinsic value. If the goal was income rather than ownership, the puts should have been rolled down/out or bought back once BLZE broke the strike.